OnePay – Mobile Banking
4.8

For anyone considering OnePay – Mobile Banking, the first practical point is the cost: the app is free to download. That makes it easy to try without paying upfront, though “free” should not be read as a promise that every banking service or transaction has no cost. I’d check the terms for any financial product I planned to use rather than assuming the app’s download price covers everything.
What free access is useful for
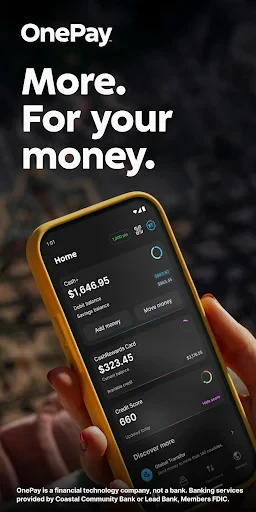
The value of a finance app depends less on the number of buttons it offers than on whether it helps with decisions I already need to make. OnePay is presented as a place to pay, bank, and build credit, so its appeal is the possibility of handling several money tasks in one app. For someone who wants fewer places to check, that consolidation can be worthwhile even before it changes any spending habits.
I would treat the app as a practical home base, not as a substitute for understanding my accounts. A single view can make it quicker to notice a balance or review activity, but it does not remove the need to check that information against the relevant account and its terms. That distinction matters when deciding whether convenience is enough to make a finance app part of a daily routine.
Where it fits among money apps
Compared with using a separate app for each financial provider, an all-in-one approach can reduce the friction of switching between screens. Compared with a dedicated budgeting app, though, a banking-focused product may not suit someone who wants extensive planning tools or detailed custom reports. I’d choose based on the task I actually need to do: quick access and payment-related banking in one place, or deeper analysis in a specialist tool.
There is also a useful middle ground. I can keep a primary bank’s app for account-specific tasks and use OnePay for the broader view or services I choose to manage there. That avoids making a complete switch before I know whether the combined workflow suits me. For financial apps, trying one role at a time is more sensible than moving every account and routine over on day one.
A realistic routine, and a few checks before relying on it
Imagine checking money before a grocery run. I might open the app to see what is available, review recent spending, and decide on a reasonable limit for the trip. Later, I could look at the transaction and consider whether it fits my weekly plan. The useful part is not a magic budgeting result; it is having a repeatable moment to check my choices. If the view does not include the account or activity I need, I should use the relevant provider directly rather than assume the app shows everything.
For a less obvious but useful habit, I’d compare the app’s view with my own monthly statements during the first few weeks. That helps me learn how its presentation matches the records I rely on and catch any accounts or transactions I expected to see but cannot find. I’d also keep a separate note of bill due dates until I’m confident that the reminders I need are appearing reliably. Notifications can support a routine, but they should not be my only safeguard against a missed payment.
Another trade-off is concentration: fewer apps can mean a simpler routine, but putting more financial activity behind one login makes account access especially important. I’d use the available security options, keep my sign-in details private, and avoid checking sensitive information on a device or connection I do not trust. If I prefer every provider to remain separate, or I need specialist tools that OnePay does not provide for my particular workflow, keeping my current setup may be the better choice.
A closer look at OnePay
Ever found yourself juggling multiple banking apps just to keep track of your finances? Well, let me tell you about OnePay – Mobile Banking. This app aims to simplify your financial life by bringing all your banking needs into one convenient platform. As someone who loves having everything organized and accessible, I decided to give it a try.
A Unified Banking Experience
One of the standout features of OnePay is its ability to link multiple bank accounts from different institutions. Whether you're dealing with checking, savings, or even credit cards, this app has got you covered. I found the setup process surprisingly straightforward. Just a few taps and all my accounts were synced, allowing me to see everything in one place.
Not only does this make it easier to manage my finances, but it’s also a huge time saver. No more hopping between apps or websites just to check my balances. Everything is right there, neatly organized. Plus, the app offers a sleek, user-friendly interface that makes navigation a breeze.
Smart Features at Your Fingertips
Beyond basic banking, OnePay offers a variety of smart features that really enhance the user experience. One of my favorites is the budgeting tool. It automatically categorizes your transactions, giving you a clear picture of where your money is going. This has been a game changer for me in terms of managing my monthly expenses.
The app also sends helpful notifications about upcoming bills and suspicious activity alerts, which adds an extra layer of security and peace of mind. I no longer have to worry about missing a payment or overlooking any unusual transactions. It’s like having a personal financial assistant in my pocket.
Security You Can Trust
Now, I know security is a major concern when it comes to mobile banking, and rightly so. OnePay doesn’t disappoint in this department. The app uses advanced encryption to protect your data, and they’ve incorporated biometric authentication for added security. Knowing that my information is safe allows me to bank with confidence.
Additionally, the app offers customer support that’s responsive and easy to reach. If you ever encounter any issues, help is just a call or message away. It’s refreshing to see such dedication to customer service, especially in the digital banking world.
Choosing it for the right reasons
OnePay is a finance app developed by ONE Finance, Inc. It is free, rated for Everyone, and has a 4.8 average from around 120,000 ratings. More than 5 million installs suggest that many people have tried it, but popularity alone does not tell me whether its particular mix of banking and money-management features suits my needs. I’d judge it by how well it fits the accounts and routine I actually use.
The app is a stronger fit for someone who values convenience and wants to explore a combined approach to payments, banking, and credit-building. It may be less appealing to a person who is already happy with a bank’s own tools, prefers keeping financial providers separate, or needs a specific feature that is not part of their normal experience with OnePay. Before making it the center of a financial routine, I’d confirm that the services I want are available to me and understand their individual conditions.
One practical question is whether I need to move my whole financial life into it. I would not start that way. I’d first use it for a limited task, such as checking the accounts I choose to connect or exploring a payment workflow, while keeping my existing bank access available. That gives me a chance to see whether the app’s layout and account view genuinely save effort without making an abrupt change to how I handle bills or balances.
Another question is whether it replaces a bank’s own app. I would not assume so. A consolidated app can be convenient for a broad view, while the provider’s app remains the sensible place to handle account-specific issues or verify details. Keeping both available is not a failure of the all-in-one idea; it is a useful backup when a particular task is better handled at its source.
My verdict on the value
Overall, OnePay has impressed me with its comprehensive features and emphasis on security and convenience. It’s a fantastic tool for anyone looking to streamline their financial management. Whether you’re a budgeting newbie or a seasoned pro, this app has something to offer.
If you’re tired of managing multiple apps and want an all-in-one solution, give it a shot. It might just be the financial companion you didn’t know you needed. Happy banking!
4.8
17.44K Reviews
Pros
- Intuitive user interface for easy navigation.
- Fast transaction processing times.
- Secure login with biometric authentication.
- Supports multiple currencies and accounts.
- Instant notifications for all transactions.
Cons
- Limited customer support hours.
- No offline transaction capabilities.
- High fees for international transfers.
- Occasional app crashes reported.
- Requires frequent updates.


